Related Articles
Your information to what the 2024 US election means for Washington and the world
Shares and bonds lurched lower after the Federal Reserve’s remaining coverage assembly of the year, spooked by the notion that the central financial institution could be unable to maintain chopping charges (because it had beforehand anticipated to) as a result of of still-simmering inflation.
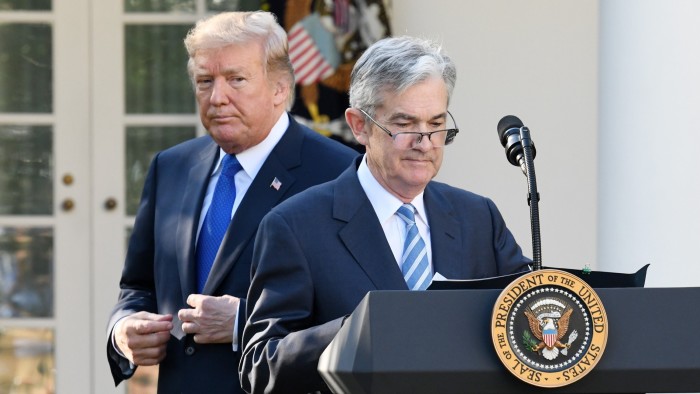
The secret’s not what Fed chair Jay Powell mentioned. It’s what he was cautious to not say however what each fund supervisor is aware of: when Donald Trump returns to the White Home this month, his financial agenda might be unhealthy for development, gasoline inflation, and even each.
So for the first time in a few years, traders have what they name “two-way threat” in the Fed coverage that drives the bond market and underpins international asset costs. The central financial institution would possibly be capable of carry on chopping — the hunch is that this is able to be Trump’s choice. But it surely’s not outlandish to counsel it’d begin elevating charges once more as a substitute. This might get vigorous.
Shares aren’t any simpler to learn. The miracle that’s the US market, recent from two years with good points of round 20 per cent every, could or could not be on borrowed time. The optimistic case is that richly valued tech corporations deserve their valuations as a result of of their earnings. “What will drive international markets will be the US,” mentioned Niamh Brodie-Machura, co-chief funding officer for equities at Constancy Worldwide. “It appears to be like costly however there’s a purpose for that.”
Some even argue {that a} new paradigm pushed by synthetic intelligence makes boring outdated enterprise and market cycles a factor of the previous — even earlier than you contemplate American exceptionalism. The pessimistic case is that that is getting foolish, AI is overhyped and one thing has to present.
My crystal ball is at the restore store so I don’t know the way this will pan out. However I do keep in mind 2022 — hardly a feat of reminiscence however nonetheless a interval that cash managers would quite neglect. Bonds and shares fell closely at the identical time — by about 20 per cent every over the year — nuking the inverse relationship that usually offers traders a security web. Development shocks and rate of interest cuts are good for bonds. Inflation and charge rises usually are not. It’s no stretch to think about this nightmare state of affairs returning.
Buyers are operating into this discipline of dangers for 2025 in barely higher form than they had been earlier in December. Just a few weeks in the past, Financial institution of America’s month-to-month fund supervisor survey discovered what it referred to as “super-bullish sentiment”. It famous that good vibes — measured by allocations to money and shares in addition to financial expectations — had intensified at the quickest tempo since June 2020. This was a bit too fizzy. Fortunately — albeit painfully — the shock of the Fed’s new view of the world knocked off some of the froth.
At the identical time, although, the markets nonetheless don’t have any clue what the returning President Trump will really do. At the excessive finish, commerce tariffs of 60 per cent on imports from China and 20 per cent from the relaxation of the world are believable. Equally, so is a a lot lighter contact — a set of tariffs which can be extra symbolic than impactful. The crackdown on unlawful immigration might additionally vary from a small quantity of focused deportations to mass detainment and extreme disruption in the labour market.
This leaves traders blindfolded and tiptoeing round rakes. “‘Meh’ is the very unlikely 2025 pathway, in my opinion,” wrote Henry Neville, a portfolio supervisor at the Man hedge fund group in a recent blog. “I can see a Nineteen Seventies state of affairs of dormant, not lifeless, inflationary pressures reawakening. Each the fairness and bond markets freak like it’s 2022. However equally, it’s conceivable we get extra market-good Trump (deregulation, tax cuts, authorities efficiencies, Ukraine peace deal) than market-bad (coverage volatility, tariffs, labour market restrictions) after which we might social gathering prefer it’s 1996.” Neville leans in the direction of pessimism however fireworks lie forward in both case.
Including to the nervousness, Trump is fond of making coverage pronouncements, generally with a big market impression, in seemingly randomly timed social media posts. This technique retains rivals and adversaries off stability but in addition unnerves cash managers and injects volatility into asset costs. Fund managers usually say they know that is coming and are higher ready to disregard the noise than in Trump’s first administration. I’m not so certain. His first months in the White Home will be the check — then traders can attempt to sketch out what flavour of president they’re really coping with.
The excellent news is that whereas bonds face potential hazard from inflation, fairness hedges are moderately low cost. Gold — a bolt-hole in occasions of strife — now seems to be on the up in all weathers. Its 26 per cent rise final year outstripped the S&P 500. Assume-tank OMFIF reckons the gold in official reserves is on observe to succeed in the highest level since 1965. The upshot: cautious traders might protect themselves. They might have to.
“We have to be humble and say, ‘I don’t know the place that is going to interrupt’,” mentioned Peter Fitzgerald, chief funding officer for macro and multi-asset at Aviva Buyers in London. “The secret’s, don’t get overconfident.” Good luck.