Related Articles
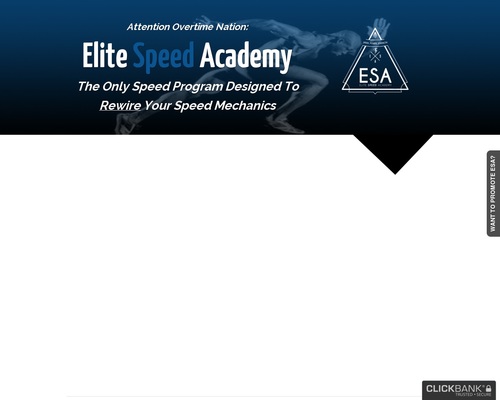
UK savers invested simply 8 per cent of their wealth straight into equities and mutual funds in contrast with 33 per cent in the US and a mean of 14 per cent throughout the remaining 5 G7 nations, in accordance with an evaluation of nationwide accounts by Abrdn.
The asset supervisor has repeatedly known as on the authorities to encourage share possession to assist stave off what it sees as a disaster in retirement. There are “questions round how far [the UK government] can assist an ageing inhabitants . . . and retirement pots will more and more fall wanting what folks want”, stated Xavier Meyer, chief government of Abrdn’s funding enterprise.
“Private financial savings and investments might want to improve to satisfy this shortfall,” stated Meyer, who prompt that Britons might look to different G7 nations for inspiration. “Taking a number of classes from our worldwide neighbours is not any unhealthy thought,” he added.

In the US, a “risk-taking tradition” and booming native stock market have pushed private wealth into equities, stated Laith Khalaf, head of funding evaluation at AJ Bell.
The S&P 500 index of huge, listed US firms has risen greater than 1,100 per cent over the previous 30 years, far surpassing related indices in the G7. Over the identical interval, the UK’s FTSE 100 index has risen simply 135 per cent.
Khalaf added that in the US, a long-standing development of “folks managing their very own pensions” utilizing 401(okay) plans had inspired people to actively handle their cash and make investments in equities.
The UK comes high of the pile for pension funds in Abrdn’s evaluation: 19 per cent of private wealth in the nation is allotted to pensions, in contrast with 17 per cent in the US and 6 per cent in Germany, the lowest of the G7.
Chancellor Rachel Reeves has tried to corral pension fund funding into UK shares to reinvigorate British firms and gas infrastructure initiatives.
Assume-tank New Monetary estimated that UK pension funds have slashed their allocation to UK equities from simply over half of all belongings in 1997 to 4.4 per cent at present — amongst outlined contribution schemes the proportion is greater, at 8 per cent.
Susannah Streeter, head of cash and markets at funding platform Hargreaves Lansdown, stated that UK pension fund cash was flowing to world markets due to the greater returns on supply. “That [discourages] firms from itemizing in the UK, and if fewer firms checklist, then there’s much less alternative for UK buyers as a result of they’re not so enthusiastic about the good points.”
The chancellor proposed a consolidation of pension schemes in November to spur home funding, however the plans have stopped wanting forcing funds to take a position in the UK.

About 15 per cent of UK private wealth is held in money, in line with the different European G7 nations, however lower than half the proportion in Japan, the place simply over a 3rd of all private wealth is in the type of money.
“Japan has been scarred by the interval from the late Eighties onwards, when the stock and property markets collapsed,” stated Darius McDermott, managing director of advisory agency Chelsea Monetary Providers. “That was adopted by a protracted interval of deflation and low rates of interest” that meant savers might maintain money with out worrying about its worth being eroded, he added.
A latest rise in inflation prompted the Japanese authorities to introduce bigger tax reliefs for investments final 12 months. In January 2024, the Nippon particular person financial savings account (Nisa) — launched in 2014 and primarily based on the UK’s Isa — was expanded with extra enticing tax exemptions. The improved Nisa provides people a lifetime tax exemption on fairness investments and contribution limits have been tripled.
The UK’s Isa scheme, now greater than 25 years old and utilized by greater than 22mn folks, has been lauded as successful — however advisers level out that two-thirds of these maintain money solely, in accordance with evaluation by AJ Bell, a monetary platform, of the most up-to-date HM Income & Customs’ information, for 2021-22.
Streeter famous that Isa thresholds have not been elevated since 2017. “I feel that’s a little bit of a disincentive, as a result of if there was a better tax-free wrapper underneath which to purchase funds in equities, it will encourage extra funding in the stock market.”
The UK is essentially in line with different European G7 nations on housing, with about half of private wealth allotted to the asset class — although in nations the place home costs are greater, residents could have no selection however to dedicate a big chunk of their wealth to bricks and mortar.
In the US, solely 1 / 4 of private wealth is in housing, a truth Abrdn’s deputy chief economist James McCann suspects is linked to the “greater fairness allocation” amongst US households and “a little bit of scarring from the monetary disaster”, which hit the US worse than different housing markets in the G7.
Abrdn’s evaluation included the full worth of properties held and didn’t subtract mortgage debt.
Myron Jobson, senior private finance analyst at funding platform Interactive Investor, stated a “bricks-and-mortar mindset” in the UK along with a powerful property market had created a technology of landlords. “And there’s the double good thing about the earnings that comes from renting that property and the capital development in your preliminary funding,” he added.
Yolande Barnes, chair of the Bartlett Actual Property Institute at College School London, stated the “vary of wealth” in a rustic was the most vital issue in figuring out folks’s asset allocation.
“Solely these in the highest wealth bands have a tendency to make use of higher-risk, higher- return investments comparable to equities in their wealth portfolios,” stated Barnes, citing research by the Decision Basis, a think-tank. “Mid-range wealth cohorts have a tendency to make use of actual property — primarily housing — way more,” she stated.
The US’s excessive fairness allocation was subsequently defined in half by its greater variety of rich people who had a a lot better propensity to take a position in equities and different high-risk devices, she added.
Abrdn stated its numbers differed from different estimates of asset allocation — comparable to the UK Workplace for Nationwide Statistics’ Wealth and Belongings Survey — due to variations in information sources, methodological assumptions and the way asset values are aggregated. It stated it had used figures from nationwide accounts as they had been “the fairest and finest solution to examine throughout nations”.
The asset supervisor will publish the figures in full on Monday, in its “Inform Sid and inform him once more” report on find out how to encourage retail participation in capital markets.